By Roya Cohen, Senior Global Real Estate Advisor, Sotheby's International Realty. Reviewed November 2026.
The purchase price is the number everyone talks about. The number that decides whether you can actually buy is the cash you need on hand, and in Manhattan it has three parts: the down payment, the closing costs and the reserves a lender or co-op board expects you to keep after closing. Planning for all three helps you identify a workable budget before you make an offer. It does not guarantee financing or board approval.
Cash paid out and reserves kept back
Planning resources = down payment + closing costs + required post-closing reserves. Reserves are assets you retain, not another fee paid at closing. The percentages below are planning assumptions, not universal requirements; ask the lender and managing agent to confirm the rules for the apartment and loan you are considering.
Part one: the down payment
Condos. Lenders set the minimum. Ten to twenty percent down is common for well-qualified buyers, but approval depends on both the borrower and the project. Some buildings and some loan programs want more, particularly in new development before a building is fully sold.
Co-ops. The building's financing limit and the lender's requirements both matter. Twenty percent is the floor at most Manhattan co-ops; 25 to 30 percent is typical; a minority of buildings require 50 percent or all cash. The building's minimum is in its house rules or offering plan and your broker should know it before you tour.
Townhouses. Jumbo-loan underwriting usually means 20 to 30 percent.
A larger down payment may lower the monthly loan payment, but also leaves less cash in reserve. Evaluate both effects rather than assuming a larger down payment always strengthens an application.
Part two: closing costs
Budget for closing costs separately from the down payment. Ask your lender and attorney which expenses are due before or at closing and whether any permitted credits or loan structures affect the cash required. They depend heavily on structure. A financed co-op closes for roughly 1.5 to 2.5 percent of the price, because there is no mortgage recording tax and no title insurance. A financed condo runs roughly 3.5 to 4.5 percent, because both of those apply. Both pay the state's mansion tax, which begins at 1 percent at $1,000,000 and rises through tiers above $2,000,000 (New York State Department of Taxation and Finance). Our closing-cost guide breaks down the main categories. These percentage ranges are estimates, not caps; price tiers, sponsor terms and building fees can move costs outside them.
Part three: post-closing reserves
This is the number buyers most often miss.
Lenders typically want to see several months of total housing payments in reserve after closing; six to twelve months is a common range for jumbo loans.
Co-op boards want more. Many Manhattan boards look for one to two years of loan plus maintenance payments remaining in liquid assets after the down payment and closing costs. Liquid means cash, money market funds, stocks and bonds in taxable accounts. Retirement accounts are listed but usually discounted, sometimes to zero, because they cannot be spent freely. Equity in another home rarely counts.
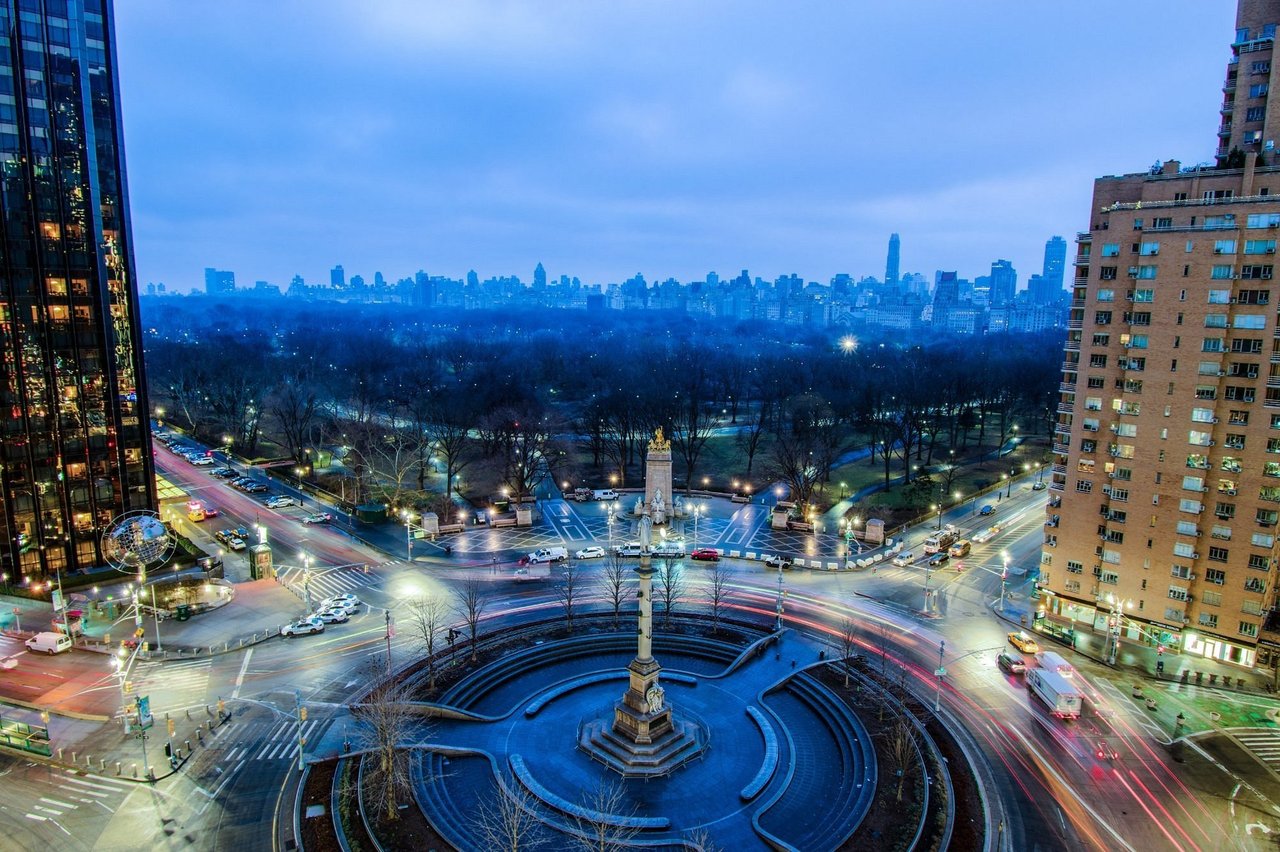
A board's reserve expectation is informal and rarely published, which is why experience in specific buildings matters. We know, for example, how the boards at the Lincoln Square and Upper West Side co-ops where we sell most often tend to read a file.
Example: a $1.2 million co-op
Assume a two-bedroom at a Lincoln Square doorman co-op, $2,400 monthly maintenance, a $900,000 loan at an illustrative 6.5 percent fixed rate over 30 years (about $5,690 per month).
Component | Amount |
|---|---|
Down payment (25%) | $300,000 |
Closing costs (about 1.8%) | about $22,000 |
Reserves: 24 months of loan plus maintenance ($8,090 x 24) | about $194,000 |
Illustrative liquid resources needed | about $516,000 |
Under these assumptions, $350,000 would not cover the down payment, estimated costs and the full 24-month reserve target. About $516,000 covers the illustrated arithmetic, but neither that amount nor $520,000 guarantees approval: the board and lender assess the complete application.
Example: a $3.5 million condo
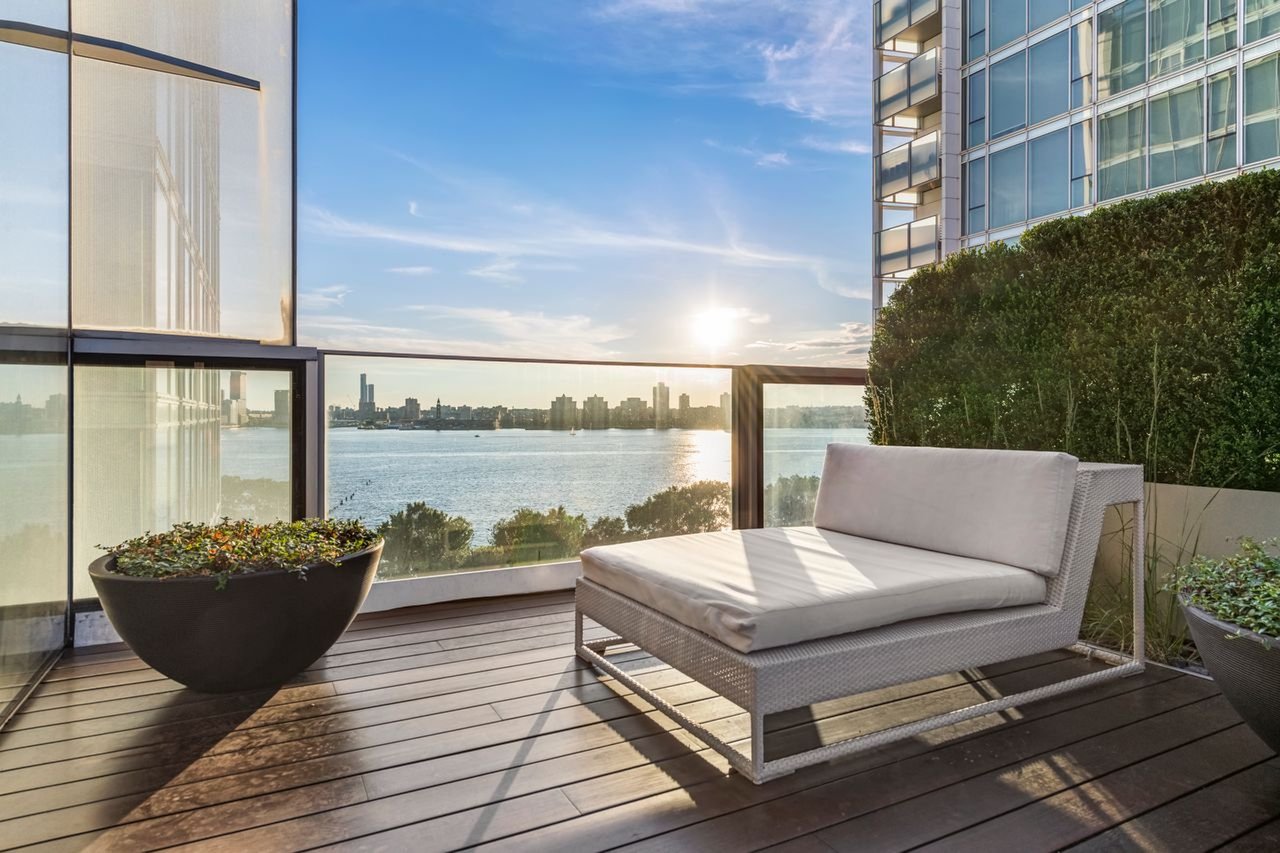
Assume a Riverside Boulevard condominium, $4,500 per month in common charges and property taxes, a $2,800,000 loan at the same illustrative 6.5 percent rate over 30 years (about $17,700 per month).
Component | Amount |
|---|---|
Down payment (20%) | $700,000 |
Closing costs (about 3.9%) | about $135,000 |
Reserves: 12 months of loan plus carrying costs ($22,200 x 12) | about $266,000 |
Illustrative liquid resources needed | about $1,100,000 |
The 12-month reserve figure is an assumption for this example, not a universal condo or lender requirement. Confirm the lender's underwriting and the building's application requirements; this example also excludes moving, renovation and a separate personal emergency budget.
Gifts, guarantors and co-purchasers
Gift funds from a relative are accepted by most lenders and most buildings, provided they are documented with a gift letter and a traceable transfer. Guarantors are accepted by some co-ops and refused by others. Co-purchasers (a parent on the stock certificate who does not live in the apartment) are prohibited by many co-ops and allowed by some. If any of these is part of your plan, the building must be chosen around it. We screen for this before showing anything.
What counts as liquid, and what does not
Count: checking and savings, money market funds, CDs, brokerage accounts holding stocks, bonds and ETFs.
Count at a discount or not at all: 401(k) and IRA balances, equity in other real estate, business ownership value, cryptocurrency, vested but unexercised stock options.
If most of your net worth sits in the second group, ask how each proposed lender and building will treat those assets before choosing a purchase structure. A larger down payment can reduce the monthly loan payment while also reducing the assets left after closing.
Working backward from your cash
The most useful planning exercise is to start with the cash you have and work backward. Take your liquid assets, subtract the reserves a board or lender will want, subtract closing costs, and what remains is your maximum down payment. Divide by the minimum down-payment percentage for your target building type and you have a first-pass price ceiling, which must be recalculated as the price, loan payment, tax tier and reserve target change. It is often lower than a mortgage pre-approval suggests, and it is the number that actually gets you to a closing.
Want us to run this for your situation? Call 646.599.7686 or request a consultation. Share your target price, financing plan and the listings you are considering, without sending sensitive financial documents through the initial inquiry. We can help organize a preliminary budget for your lender and attorney to confirm.
Frequently asked questions
How much cash do Manhattan buyers need?
Plan for three things: the down payment (10 to 20 percent for condos, 20 to 30 percent or more for co-ops), closing costs (roughly 1.5 to 2.5 percent for co-ops, 3.5 to 4.5 percent for condos) and post-closing reserves (several months for a lender, one to two years for many co-op boards).
What is post-closing liquidity?
The liquid assets you have left after paying the down payment and closing costs. Co-op boards use it to judge whether you can keep paying maintenance through a job loss or market downturn.
Do retirement accounts count as reserves?
Usually only partially. Many boards discount 401(k) and IRA balances or exclude them because they cannot be spent without penalty.
Can I put 10 percent down on a co-op?
Rarely. Most co-op boards require at least 20 percent, and many require 25 percent or more. Do not assume a particular percentage works: confirm both the building's financing limit and the lender's approval.
Can my parents gift my down payment?
Most buildings and lenders accept documented gift funds. Guarantors and co-purchasers are building-specific; some co-ops prohibit them entirely.
Does pre-approval establish my budget?
No. Pre-approval reflects the lender's view of your income and debt. It does not account for a co-op board's stricter ratios or reserve expectations, and it does not include closing costs.
Related guides
- NYC buyer closing costs in 2026
- What Manhattan co-op boards look for in a board package
- Co-op vs condo: the real cost comparison
- Upper West Side neighborhood guide
- Our buyer's guide
Sources
- New York State Department of Taxation and Finance, TSB-M-19(1)R: https://www.tax.ny.gov/pdf/memos/real_estate/m19-1r.pdf
- NYC Comptroller, mortgage recording tax rate table: https://comptroller.nyc.gov/reports/nyc-for-all-the-housing-we-need/
- The Roya Cohen Team transaction experience, 2004–2026